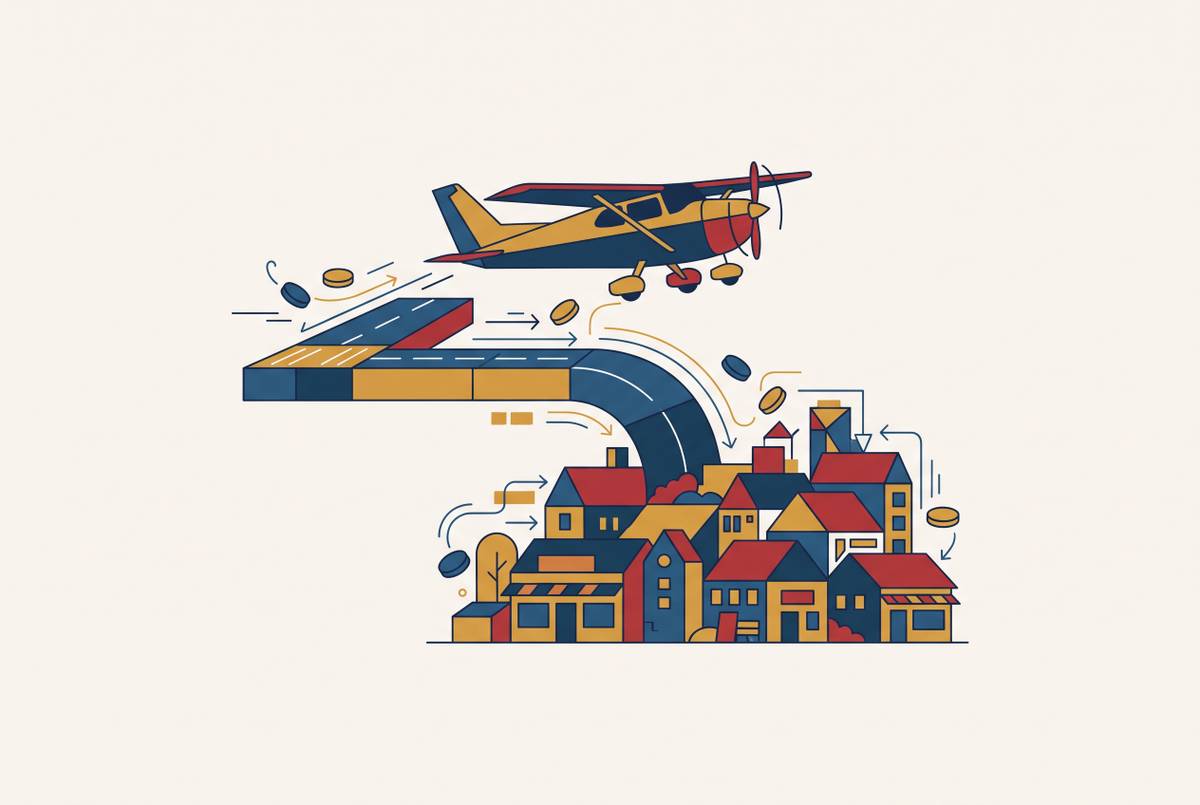
Revenue Streams Available to Small General Aviation Airports
Fuel fees, hangars, and land leases can narrow the funding gap.
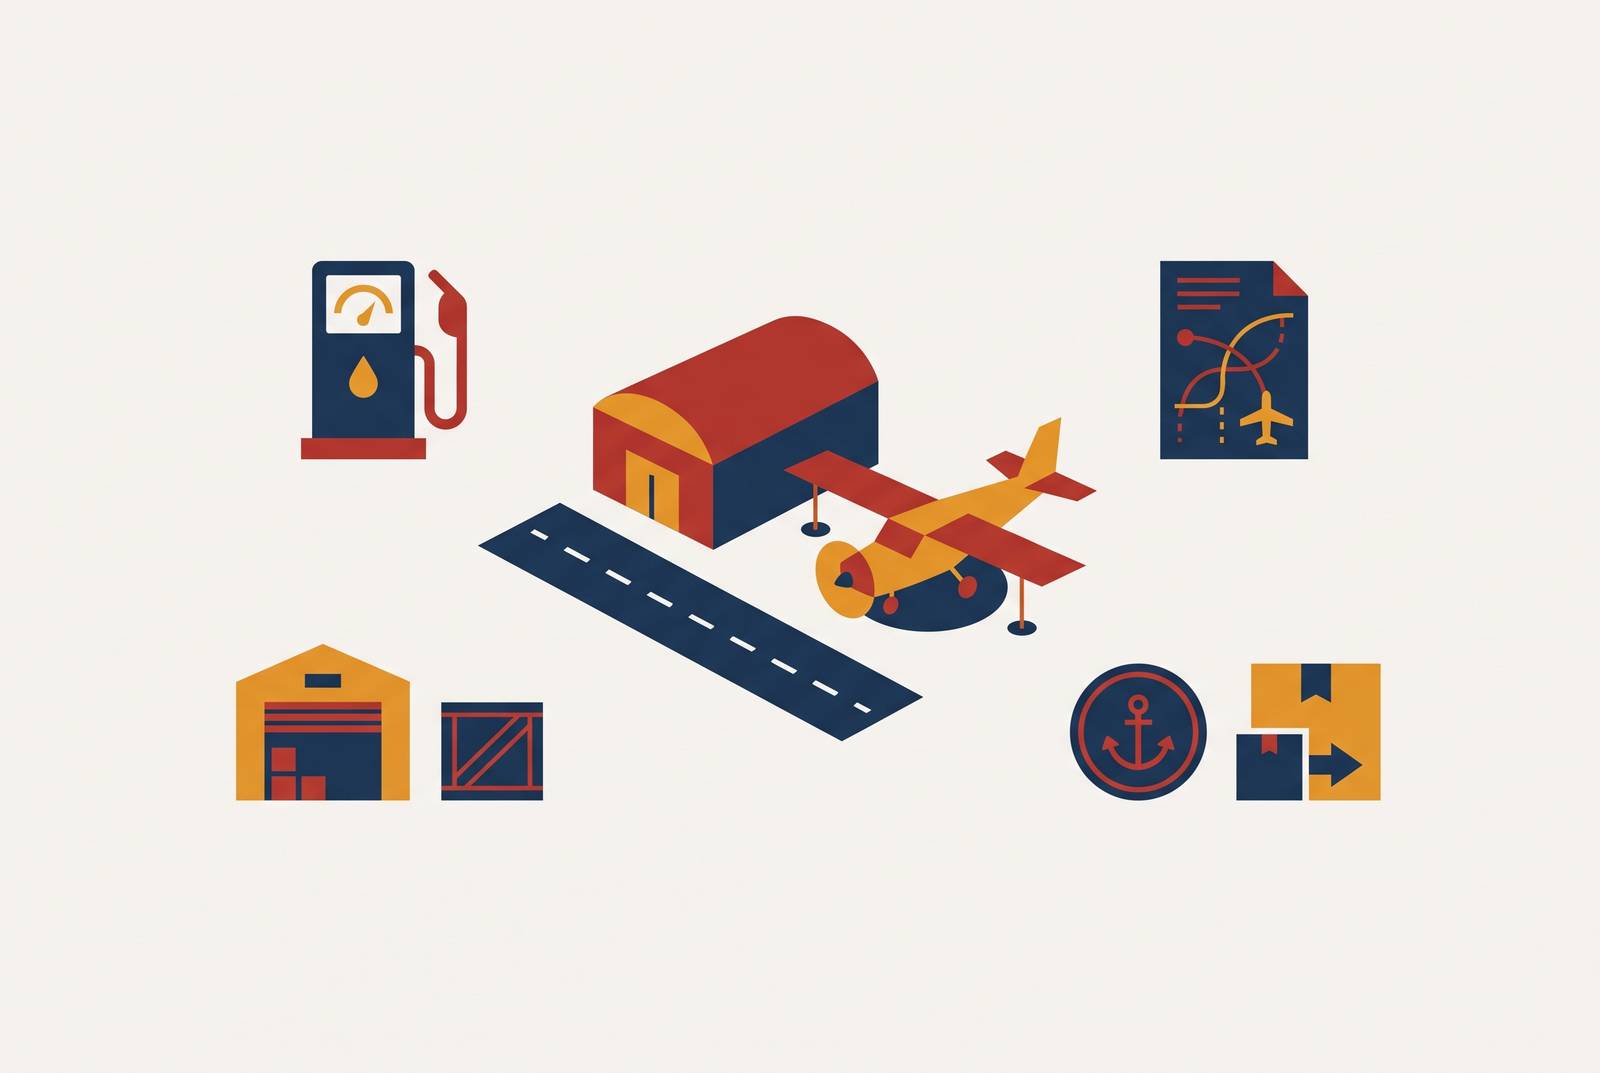
Small general aviation airports can bring the income they earn closer to their costs by drawing on all their revenue sources, including fuel fees, hangars, land leases and new aviation uses. Digital ATC infrastructure can support that strategy by making safety coverage more affordable and enabling new uses. FAA Airport Improvement Program funding helps pay for capital improvements at NPIAS airports, but that description alone does not show whether a given digital tower system is eligible.
Why small GA airports face a structural revenue problem, not just a budget shortfall
Small GA airports are capital-intensive enterprises whose FAA safety and operational requirements routinely cost more than their own revenue can cover. Their dependence on federal grants is therefore structural. The funding relationship is inverted by airport size, with smaller airports relying more heavily on outside support than large hubs. They have few local sources of income to pay for infrastructure whose requirements do not fall at the same rate as traffic.
Even rising rents do not necessarily close that gap. Lease and hangar revenues typically escalate with the Consumer Price Index, while construction cost inflation has historically run roughly twice that rate. Shortages of concrete, asphalt, steel and skilled labor push replacement costs beyond what lease income can buy. Because external funding is constrained and aeronautical revenue offers only a narrow set of collection points, the full revenue menu becomes the main lever operators control.
The core aeronautical revenue toolkit and why fuel dominates it
The main sources of aeronautical revenue are fuel flowage fees, aircraft parking and storage fees, landing fees, and aeronautical ground and building rents. Fuel dominates because refueling creates recurring, volume-based business for fixed-base operators, or FBOs. The airport generally captures that activity through a per-gallon flowage fee paid by the FBO. That distinction matters when structuring an FBO ground lease, because fuel sales and airport fuel income are not interchangeable.
FBOs also earn revenue from parking, hangar rentals, ground handling and passenger amenities. Airports earn their share through ground lease payments and concession or percentage fees. Landing fees provide another source, but small-airport traffic volumes and aircraft weights cannot produce the totals available at major commercial hubs. The airport exchanges access to infrastructure for lease and flowage income, while the FBO exchanges part of its revenue for access to aircraft traffic. Under this partnership, the airport’s income depends on both how busy the field is and how well the FBO does.
Safe, efficient operations help sustain that partnership. Digital tower technology designed for non-towered fields, including systems built by General Aviation, can improve field-level safety and efficiency and make an airport a more attractive FBO location. That operational support does not replace the underlying need for traffic.
Hangar leasing as a revenue source and the sublease problem that erodes it
Hangar leasing is a significant and growing opportunity, supported by a large registered aircraft base in the United States. North America has the largest share of the multi-billion-dollar global market for aircraft hangar leasing. Local demand and the type of space shape the hangar rental income individual airports can capture. In 2026, T-hangar rents for single-piston aircraft vary widely from place to place, while rents for jet-capable box hangars are much higher. Airports that own their inventory can capture the rent associated with those different uses directly.
Private development changes where that income goes. When private owners of hangars on land leased from an airport sublease space below market rates, they keep the rental income. That space also competes with airport-owned or publicly developed hangars for the same aircraft demand. Subleasing therefore directly affects airport revenue.
Direct ownership captures full hangar lease revenue, while leasing ground to developers recovers income through ground rents and flowage fees. The latter is simpler to administer but leaves the airport more exposed to competition from below-market subleases. Public-private partnership development offers a middle path, with private money paying for construction and no need for the airport to take on construction debt. How well it works depends in part on the terms the parties agree to guard against below-market subleasing.
Non-aeronautical land leases and the institutional tenant model
Land leasing broadens the revenue base beyond fees tied to individual aircraft operations. FAA policy permits airports to earn revenue by renting property they do not need for aviation use to non-aviation-related developers if they first get written FAA approval or consent and charge fair market value rent. Airports that have not inventoried their available non-aeronautical land may therefore be leaving a controllable source unused. Institutional education tenants offer a related model for anchoring long-term lease income, although aviation education facilities are not necessarily non-aeronautical uses.
Dubuque Regional Airport illustrates the institutional model, with the important qualification that it is a city-managed primary commercial service airport. Leases account for roughly a quarter of its budgeted operating revenue. The University of Dubuque lease anchors a significant projected FY2027 revenue line. The City of Dubuque’s Airport Policy Book records the university’s fall 2024 announcement of investment in its aviation academic program and airport facilities, including two new hangars. The case shows how one institutional relationship can support both rent and capital development.
Aviation academic programs, flight schools and aviation-adjacent training facilities are natural prospective tenants for GA airports with underused land. Long-term plans for capital spending must still allow for that gap between what rent brings in and what it can buy. Land leases can bring in steady income even when it falls short of what replacements cost. Emerging aviation uses extend the menu beyond that stable but bounded base, although their revenue is less proven.
Emerging revenue streams through SAF infrastructure, electric charging, and vertiports for AAM
Sustainable aviation fuel, electric aircraft charging and advanced air mobility are being explored as ways to earn money, but their returns remain uncertain. Each calls for decisions about infrastructure now based on demand in the future. For sustainable aviation fuel, or SAF, the relevant facilities include storage, blending and dispensing. The revenue mechanism resembles conventional fueling through flowage fees on delivered volume. Those fees could carry higher per-gallon rates reflecting SAF’s price premium over conventional Jet-A as operators pursue emissions compliance.
Airports installing charging infrastructure can charge access or usage fees as electric aircraft enter the market. The capital requirement is modest relative to conventional fuel infrastructure, and available electrical capacity can allow an airport to move quickly. The distinction is important because charging creates a new collection point rather than simply changing the fuel passing through an existing one. Its contribution remains dependent on aircraft demand, limiting its ability to replace established income.
Advanced air mobility, or AAM, adds potential land lease and facility fee income through vertiports and eVTOL facilities. The service model is expected to use smaller airports, and operators already plan to rely on remote and digital tower technology for vertiport infrastructure. Digital ATC capability can therefore help position a GA airport as a credible AAM partner. This connects revenue development to operational infrastructure that some prospective users will need before they can operate. It also highlights the risk from insufficient communication between pilots at airports that cannot afford ATC coverage today.
How the chronic revenue gap creates unaddressed safety risk at uncontrolled airports
The revenue gap has an operational consequence when airports cannot fund the infrastructure needed to address known safety risks. At non-towered fields, insufficient communication between pilots operating in the same area is the most common cause of incidents near non-controlled aerodromes. Near-collisions occur at roughly twice the rate when a pilot has no prior warning of other traffic through radio or a traffic alerting system such as TCAS. The mechanism is a failure of self-separation.
The FAA Safety Team reported that severe Category A and B incursions rose sharply in 2025 even as total incursion events fell slightly. The trend establishes a severity concern, with the notice’s use of fiscal or calendar year unspecified and the share occurring at non-towered airports still unquantified. For those fields, insufficient communication between pilots is the particular exposure that ATC coverage can address. FAA countermeasures aimed at complex geometry at busy, towered airports have largely overlooked how non-towered fields work.
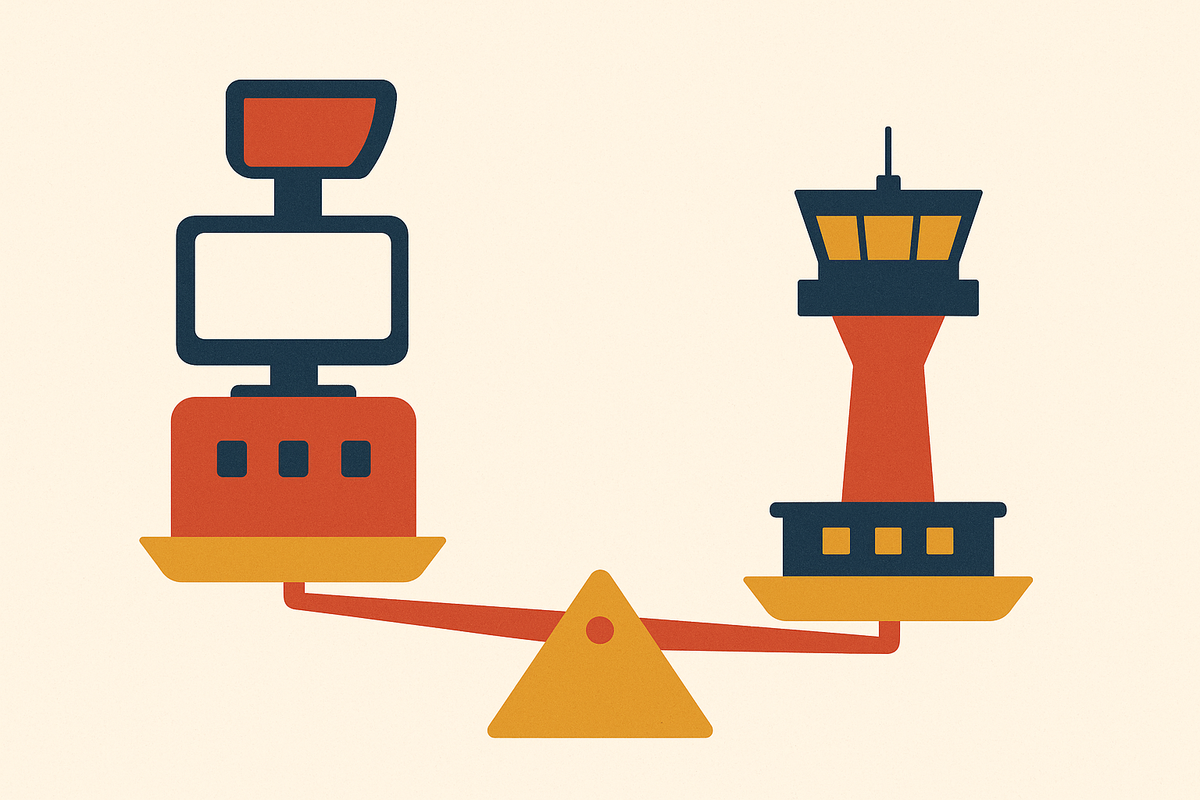
Modern ATC is among the infrastructure needs that cost enough to strain small airport budgets. General Aviation builds affordable digital ATC towers for the 90% of U.S. airports in the National Airspace System that currently have no tower. Affordability matters because traditional tower economics can leave a known safety need beyond an airport’s financial reach. The practical question is what adding coverage costs, and whether a different delivery model fits GA airport resources.
What does digital ATC coverage cost compared with a manned tower?
Johnston Regional Airport (JNX) and Raleigh Executive Jetport have FAA approval to build ATC towers that are expected to cost between $10 million and $20 million to construct. A digital remote tower is estimated to cost roughly half that amount. These estimates show the scale of the alternative, though costs vary by airport. Airports can cut their costs further by sharing remote operations. Digital towers change the cost structure as well as lowering construction costs.
A digital tower uses high-definition cameras, radar, sensors and integrated data feeds to give controllers real-time situational awareness. Controllers can work on-site or from a remote center connected through a secure data communications network. The airport sensor array and controller working position are the two core components. This arrangement requires a smaller airport footprint than a traditional tower cab. A shared center also reduces the staffing barrier for airports that cannot individually justify a dedicated position.
Avinor’s Bodø Remote Tower Centre already serves 14 airports and has plans to expand. Its first airport entered service in October 2019, and all initially planned towers were remotely managed by April 2025. Nav Canada’s digital aerodrome tower in Kingston provides a second example, using 360-degree cameras, infrared imaging and AI-driven tracking. Controllers in Kingston are planned to oversee Hamilton Airport once testing and regulatory approvals are complete. That qualification distinguishes planned cross-airport coverage from an already completed deployment.
For GA airports, the financial case combines lower capital demands with the possibility of shared staffing. The resulting coverage can also support the AAM uses described earlier. Airports adding digital ATC become more attractive to FBO operators, AAM tenants and federal grant programs focused on safety modernization.
Matching revenue strategy to the federal funding environment airports will actually face
The federal capital pipeline is tightening while airport needs are rising. ACI-NA’s 2025 infrastructure needs report identifies FY2026 as the final IIJA-funded installment of supplemental airport grants. Airports whose capital plans relied on that stream must replace the capacity after it ends. The same report documents that the Passenger Facility Charge has lost more than half its purchasing power since Congress last changed its ceiling in April 2000. At airports with few enplanements, PFC income does little to make up for the loss.
The Airport Improvement Program remains part of the funding picture, but its scale depends on congressional authorization and appropriations. NASAO’s 2026 Legislative Agenda prioritizes a robust annual AIP funding floor and directing half of supplemental discretionary grants to nonprimary, nonhub and small hub airports. That position recognizes the gap without guaranteeing an award or a future funding level. AIP supports capital improvements at NPIAS airports, and the FAA’s AIP Handbook explains available funding. Neither that general program scope nor the tower construction approvals cited earlier establishes digital-system eligibility, grant coverage or vendor grant-application services.
Self-generated revenue and affordable infrastructure therefore have to work together. Fuel and FBO fees anchor the operating base, while active hangar management and institutional land leases broaden what the airport captures. SAF, charging and AAM offer additional possibilities where demand supports investment. Digital ATC can make those uses more practical while addressing safety needs at a lower estimated capital cost than a traditional tower.
Sources
- MODERN AIRPORTS FOR A STRONGER AMERICA UNLOCKING OPPORTUNITIES
- Airport-Generated Revenue or Operating Revenue
- Federal, State and Local Funding Sources for Airports
- Revenue and Financing Alternatives for Medium and Small U.S. Airports in an Evolving Aviation Landscape - RIP
- ASRS Database Report Set Non-Tower Airport Incidents